
Amazon: undisputed leader, but the momentum is fading
Amazon splits into two lines in the monitor: first-party retail with a 17.2 percent market share and Marketplace with 46.1 percent. Together that's 63.3 percent, up 4.9 percent in revenue year on year. It remains in a different league from everything that follows.
What stands out is the movement, not the size. Plus 0.5 percentage points of market share means Amazon is barely expanding its position anymore. The business grows with the market, not beyond it. For sellers, the read is straightforward: Amazon is non-negotiable as a channel, but the platform no longer hands you incremental reach simply for being there.
Temu and Shein: a jump that isn't only about more buyers
Foreign online sellers shipping into Germany from abroad account for around 11.8 percent of online volume, roughly 10.9 billion euros. Most of that comes from Temu and Shein: an estimated 4.7 billion euros, about 5 percent of total online retail.
The real story is in the change. In 2024 the estimate for Temu and Shein stood at 3.0 billion euros; in 2025 it reached 4.7. That's a gain of about 57 percent in a single year. It isn't driven by buyer numbers alone, which rose modestly from 14.4 to 16.0 million. The bigger lever is order value: average spend per order climbed from 24.95 to 34.15 euros. These platforms aren't just selling more, they're selling pricier. That works out to roughly 460,000 parcels reaching German households every day.
Across the EU the reach is substantial. Temu had 129.7 million monthly users in 2025 (97.3 million in 2024), Shein 155.7 million (130.5 million in 2024). Germany is Temu's largest EU market at 20.9 million monthly users.
Perception stays split, and that's the part brand sellers should weigh. Among non-buyers, doubts about product quality are rising: 59 percent cite quality as their reason not to order from Temu (55 percent in 2024). Those who do buy are satisfied: 68 percent of buyers would order again, 51 percent recommend Temu. People who know the platform but haven't bought judge it the opposite way, with 67 percent advising against it. Temu retains its buyers but doesn't convert the skeptics.
One classification detail from the monitor is easy to miss and worth your attention. Temu and Shein are still counted as online players rather than marketplaces, because their goods come almost entirely from Asian suppliers. The HDE states plainly that this is changing. Once these platforms admit European third-party sellers at scale, they become marketplaces in the classic sense, and a possible sales channel for international brands rather than only a source of price pressure.
Amazon Haul: the answer in the budget segment
Amazon launched Amazon Haul in Germany in June 2025, a low-price offer positioned directly against Temu and Shein. Four months after launch, awareness already stood at 47 percent and 13 percent had bought. 51 percent of those who didn't yet know the concept find it interesting, and 59 percent of Haul buyers order at least once a month.
In the monitor, Amazon Haul counts toward Amazon Marketplace. That reinforces a dynamic already in motion: Amazon is defending the mid-price segment and now occupying the bottom one that used to belong to Temu and Shein. If you sell on Amazon, you've gained a new competitor inside your own storefront.
TikTok Shop: small in volume, fast in reach
TikTok Shop is classified as a marketplace or platform in the monitor, because German and European retailers and brands act as anchor sellers, much as they do on Amazon. Revenue reached around 220 million euros in 2025 (PwC estimate). Measured against Amazon that's small; measured against half a year on the market, it's a lot.
The speed shows in awareness: half a year after launch, 52 percent of internet users knew TikTok Shop and 9 percent had bought there. Average purchase value sits at 59 euros, higher than Temu and Shein. The most-bought categories are clothing and accessories, cosmetics and care, sport and leisure, consumer electronics, and drinks and snacks.
TikTok Shop runs on a different mechanism than the budget platforms. The purchase grows out of content and discovery, not price. That fits the channel's role: 66 percent of 16-to-19-year-olds use TikTok, and across all age groups, 13 percent have already bought a product after a social media post drew their attention. The highest figure comes from 30-to-39-year-olds at 23 percent, not the youngest cohort. Social commerce isn't a teenagers-only phenomenon.
What this means if you're entering Germany
Three takeaways come straight out of the data.
First, marketplace presence isn't optional. When 56.7 percent of online sales flow through platforms, the question isn't whether to be on them but which ones, and with what logic. Amazon stays the mandatory field, yet defending your share there is getting harder now that Amazon occupies the budget tier itself with Haul.
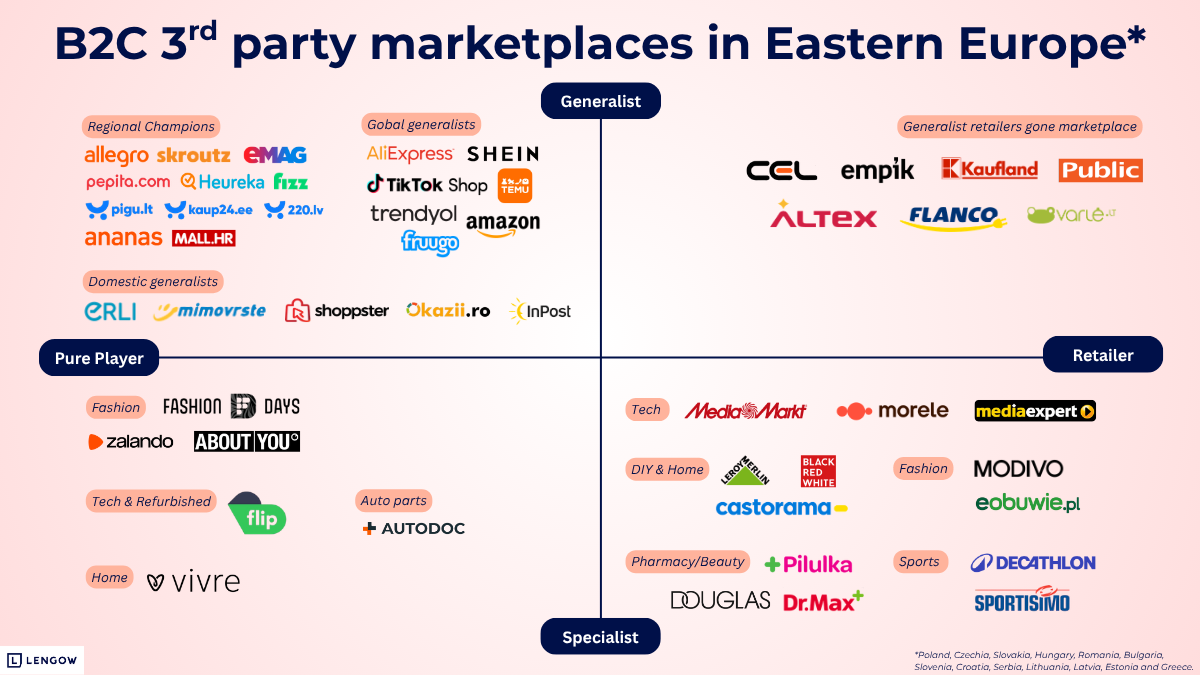
Second, the market is fragmenting along different operating logics. Amazon demands clean product data, price and availability discipline, and competition over the buy box and ranking. TikTok Shop demands video, creators and content that triggers discovery. Temu and Shein set the price frame and, once they admit European sellers, will become another channel with its own requirements. A single product catalog has to serve all of these in parallel, each with its own format and its own rules. This is where multichannel either scales or collapses into data chaos.
Third, growth is coming from order value, not just new buyers. On Temu and Shein, the average basket rose by roughly a third. For brand sellers that means even the cheap platforms have outgrown pure impulse buying and are binding volume that's missing elsewhere.
The next shift is already visible
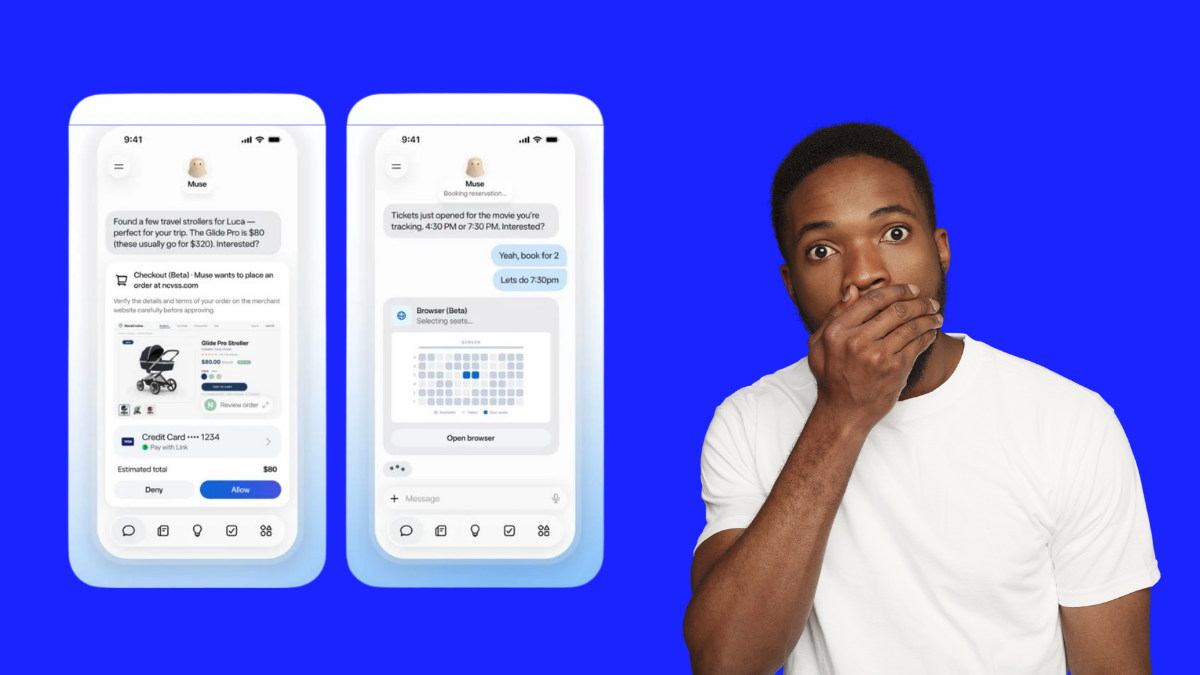
One development connects all these platforms to what comes next. 35 percent of consumers already use AI chatbots for product research, mainly to compare features, quality and price. The HDE outlines four scenarios for agentic commerce, up to an AI agent that selects, compares and buys on its own. The decisive line from the report: in that scenario, visibility depends on platform logic, not on SEO or the design of your storefront.
That's the same discipline that already decides marketplace success today. Structured, machine-readable, complete product data is the precondition for being found on Amazon, surfaced on TikTok, and tomorrow even considered by an AI agent. The platforms change; the requirement stays the same.
Source: HDE Online-Monitor 2026, published by the Handelsverband Deutschland (HDE) and produced by IFH Köln. All revenue figures are net.

Adrian Gmelch
Adrian Gmelch is Director of Content at Lengow, where he leads content strategy while staying firmly hands-on: reading the research, and tracking the trends that matter before they go mainstream.
Table of content
Is your catalogue ready for AI Shopping?
Discover what AI assistants look for, how products get selected and what you can do now to stay visible in the new shopping journey.