One reading note: this map only admits B2C third-party marketplaces: a professional seller has to be able to list a catalogue and own the sale to a consumer. That test removes some of the biggest names in the region: OLX, Vinted, Njuškalo, Bolha, KupujemProdajem and Bazar.bg are all classifieds or consumer-to-consumer platforms and sit outside the frame, however much traffic they pull.
The two axes to map marketplaces
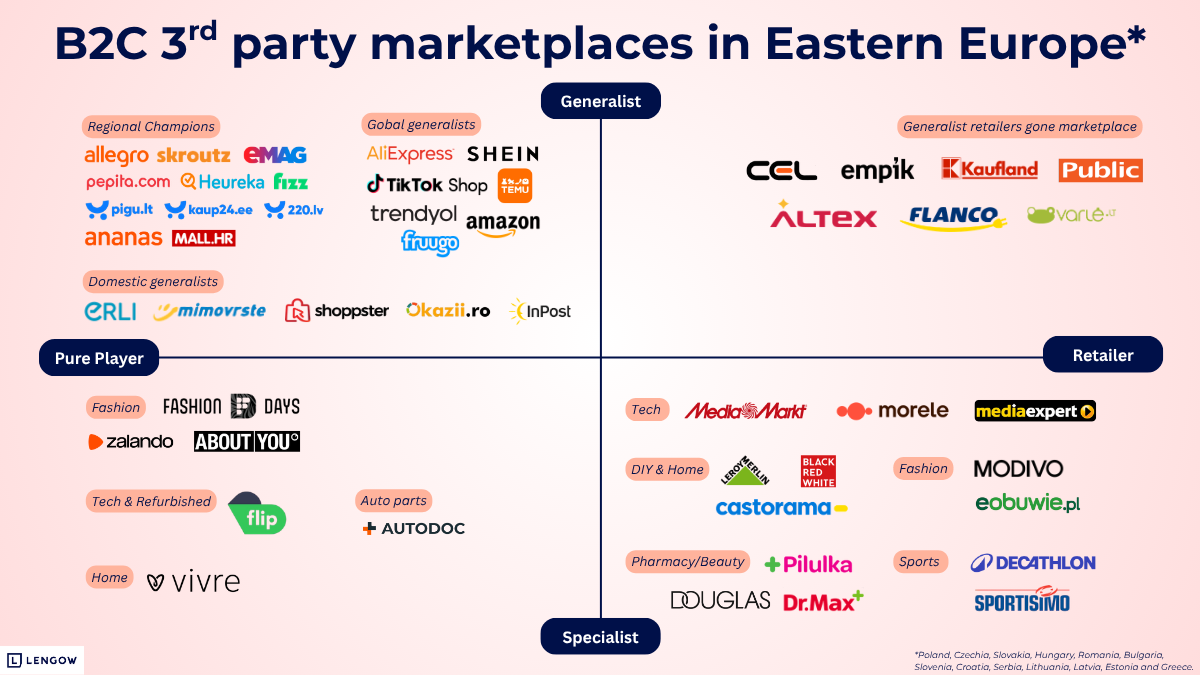
The vertical axis runs from Generalist at the top (broad, multi-category catalogue) to Specialist at the bottom (single vertical, expert audience). The horizontal axis runs from Pure Player on the left (born as an e-commerce or marketplace business, no physical retail history) to Retailer on the right (brick-and-mortar chains that opened their platforms to third-party sellers).
These axes cut to the two most structurally important questions about any marketplace: what it sells, and where it came from. Ask them across thirteen countries and the answer produces a shape that exists nowhere else in Europe. The top-left quadrant, which in Paris or Berlin belongs to Amazon, eBay and the Chinese platforms, is here crowded with companies headquartered in Poznań, Bucharest, Prague, Athens, Vilnius, Budapest and Belgrade.
Top-left: the champions that grew up at home
Allegro anchors the region. Founded in Poznań in 1999, it connects more than 21 million active buyers with over 163,000 merchants across Poland, Czechia, Slovakia and Hungary, and its 2024 GMV of 12.8 billion euros is larger than the next ten platforms on this map combined. In March 2026, Mutares completed the purchase of Allegro's Slovenian and Croatian operations, which is why Mimovrste and Mall.hr now appear as independent names.
eMAG plays the same role from Bucharest, with far more infrastructure behind it: the marketplace, the Sameday courier and lockers, Fashion Days and the refurbished business Flip. It holds over 30% of Romanian e-commerce, leads Hungary with 438 million euros of GMV and is the strongest marketplace in Bulgaria.
Heureka and Skroutz both started as comparison engines. Heureka is now the largest marketplace in Czechia by GMV at 1.6 billion euros and operates in nine countries. Skroutz serves around 2.5 million active users through approximately 9,000 merchants, with a 2024 GMV of 1.3 billion euros. In May 2026, Blackstone agreed to acquire a majority stake from CVC, in a deal Bloomberg reported at 635 million euros including debt. Skroutz already operates in Cyprus, Romania and Bulgaria.
The Baltics belong to one company under three flags. Pigu.lt, 220.lv and Kaup24.ee are the local faces of PHH Group, with more than 4,000 sellers on a shared marketplace. You list in Lithuanian first and the other two markets open from there. Elsewhere, Pepita.com (2,400 partners) sells from Hungary into Germany and Austria, Ananas carries Serbia with 1,500 merchants, and Shoppster is one of the few places in Serbia where a foreign brand can list without a local partner. In Poland, Erli charges no standard commission and lives off seller subscriptions, and InPost Buy, live since March 2026, earns only from delivery fees with roughly 4,000 merchants connected.
The global generalists sit next door. Almost 94% of what Polish shoppers spend abroad lands on Chinese stores, and in Bulgaria Temu is the most visited marketplace site, ahead of eMAG. Trendyol is the fastest riser, with 223 million euros of GMV in Romania. TikTok Shop opened in Poland on 15 June 2026 with a "Sell Across Europe" tool that lets one seller registration cover several markets. Amazon appears for Poland alone, in third place behind Allegro and AliExpress.
Top-right: seven retailers, most of them Romanian
This is the quadrant that most separates Eastern Europe from the West. In France or Germany, the hypermarkets and department stores converted to marketplaces years ago. Here, most retailers never did.
Kaufland is the exception that proves it. The Schwarz Group chain runs seller storefronts in Poland, Czechia and Slovakia, and its Polish marketplace revenue has grown 322% since launch. Note what is missing: Kaufland has more than 200 stores in Romania and 70 in Bulgaria, and no marketplace in either. For a Western seller, its Polish and Czech storefronts are a materially less crowded shelf than Allegro.
Romania supplies three of the remaining six. CEL.ro grew out of an IT retailer into a platform with around 1,800 partners and more than a million products, worth 162 million euros of GMV. Altex and Flanco, the country's two largest electronics chains, both opened their sites to third-party sellers. Nowhere else in the region did the national electronics retailers make the same move.
Empik, founded in 1948 with more than 350 stores, generated 377 million euros of marketplace GMV in 2024 and has pushed far past books into toys, sport and beauty. Public, part of Greece's Olympia Group, did the same from a media and electronics base and now clears 224 million euros of GMV across home, toys and beauty. Varlė is the Lithuanian entry, an online department store with 18 pickup shops, around 600 marketplace partners and two million products, and the only retailer on the Baltic side of the map.
Bottom-left: six names, the specialists were all imported
Compare this with the twenty-plus specialist pure players on the German map and the gap tells the story on its own. Thirteen countries produced almost no specialist marketplaces of their own, and the ones they did produce nearly all come from a single group in Bucharest.
Fashion Days, founded in 2009 and part of eMAG since 2015, runs as a standalone fashion destination across Romania, Bulgaria and Hungary. Flip, founded in Brăila in 2019 and also inside the eMAG group, is the region's Back Market, refurbishing phones, tablets and laptops with a warranty and now operating in Bulgaria and Hungary. Vivre opened its home décor and furniture platform to outside sellers and is the sole domestic name in that category.
The rest is imported. Zalando leads brand-driven fashion across most of the region. About You opened its own Polish marketplace in June 2026 with around 600 brands. Autodoc launched its Polish marketplace in July 2026, its eleventh European market, on the back of a Szczecin logistics hub, giving car parts a serious platform in a region that never built one.
Bottom-right: where the specialists sit
Nearly every vertical in Eastern Europe is served by a retailer that opened up rather than by a platform built from scratch, and the thirteen names in this quadrant make the point.
Tech is Polish. Media Expert, the country's largest domestic electronics chain, launched its third-party marketplace in autumn 2025, a move that reads as much as a defence of its own turf as an expansion. MediaMarkt went live in Poland in May 2025 and holds 110 million euros of GMV in Hungary. Morele, originally an electronics and appliance retailer, reached 195 million euros of GMV in 2024 and now runs home, garden and kids categories alongside.
DIY and home is Polish too. Leroy Merlin and Castorama, whose marketplace opened in January 2025, are the two French chains, and Black Red White is the domestic furniture group that followed them. Fashion belongs to Modivo and eobuwie.pl, both part of the group formerly known as CCC, which renamed itself Modivo in February 2026 and sits on roughly 1,500 physical stores across 20 markets.
Sport runs through Decathlon, open to Hungarian sellers since 2021 and worth 91 million euros of GMV in Czechia, and through Sportisimo, the Czech chain that opened its own platform. Pharmacy and beauty is the region's most distinctive vertical and the one most worth building for. Dr. Max runs marketplaces in Poland, Czechia, Romania and Hungary. Pilulka, founded in 2013 with 152 branded pharmacies, leads home delivery in Czechia and Slovakia and has expanded into Romania and Hungary. Douglas brings its Polish marketplace to the same shelf. Online pharmacy is more structured here than in most of Western Europe.
Four things the map shows
Cross-border is built in, and it runs on local rails
One Allegro integration reaches Polish, Czech, Slovak and Hungarian buyers. One eMAG integration covers Romania, Hungary and Bulgaria. One PHH Group account serves all three Baltic states. Heureka adds Slovenia and Croatia. That is a structural advantage this region offers and Western Europe does not, and it means a seller's first decision is which regional champion to sign with, not which country to enter.
Four countries have no marketplace of their own
Bulgaria, Slovakia, Latvia and Estonia produce nothing that qualifies for this map. They are served entirely by neighbours: eMAG in Bulgaria, Allegro, Heureka and Kaufland in Slovakia, PHH Group in the Baltics. Treat them as extensions of the platform next door, because that is already how their shoppers treat them.
The Chinese layer is permanent
AliExpress, Temu, Shein and now Trendyol capture the overwhelming majority of cross-border spending across all thirteen markets. A pricing strategy that treats them as a passing disruption rather than a fixed feature of local price expectations will misread the region.
Poland has stopped being a one-platform market
Kaufland in 2024, Castorama in January 2025, MediaMarkt in May 2025, Media Expert in autumn 2025, InPost Buy in March 2026, TikTok Shop and About You in June 2026, Autodoc in July. Seven launches in two years. For a brand weighing entry, easier doors now exist alongside Allegro, and that window will not stay open indefinitely.
What to do with this map
Thirteen countries, no single playbook. Before you sign with anyone, four things are worth settling: what each platform is actually for, which ones are really marketplaces, what local tax and payment rules require, and in which order to sign.
Clarity: purchase intent is built into most of these platforms. A Pilulka visitor is buying pharmacy. A Sportisimo shopper is in sports-purchase mode. A Flip user wants refurbished. The generalist tier is concentrated enough that four or five integrations cover the majority of reachable demand across thirteen countries.
Complexity: check who is really a marketplace before you build a plan around them. Alza is not the Czech Allegro. Notino is not a beauty platform open to sellers. OLX is the second most visited shopping site in Poland and it is not on this map. Getting that distinction wrong costs a quarter of planning time in a region where it is less obvious than it looks.
The regulatory and payment layer: KSeF e-invoicing in Poland, RO e-Factura in Romania and myDATA in Greece are prerequisites, not options. Cash on delivery still accounts for roughly 60 to 65% of Romanian orders, which changes how you model working capital before it changes anything else. Serbia sits outside the EU with its own customs and VAT treatment, and most pan-European platforms do not serve it, which is part of why Ananas and Shoppster exist at all.
Strategy: be regional first and category-led second. Sign the champion that covers the largest block of countries, then layer the specialist retailers where category fit justifies the integration cost. The thin bottom-left quadrant means fewer niche audiences reachable through dedicated platforms and more dependence on generalists and converted retailers, so platform selection carries more weight here than in France or Germany.
A region that rewards knowing who is who
Eastern Europe is the only part of the continent where domestic platforms became the regional operators, where the top-left quadrant belongs to Allegro, eMAG, Heureka and Skroutz rather than to Amazon, and where the specialist pure player quadrant is nearly empty because the generalists got there first.
That last point is the one to hold on to. The categories that are open (refurbished electronics, car parts, online pharmacy, home décor, sport) have very few incumbents, and in a region where seven marketplaces launched in Poland alone within two years, that emptiness is the opportunity. The brands that move now will be competing against a map that looks nothing like the one their competitors will face in 2028.
Map compiled by Lengow, September 2026. Platform inclusion is based on confirmed third-party B2C seller activity. Price comparison engines, cost-per-click platforms, first-party retailers and consumer-to-consumer classifieds are excluded. GMV figures are ECDB 2024 data as compiled by Marketplace Universe unless otherwise stated.

Alexis Merelle
Alexis Mérelle works on content and SEO at Lengow, where he turns marketplace and pricing data into articles, and tracks what AI search is doing to product discovery.