Who is affected by these changes?
Everyone! All merchants offering B2C online services or products (sold to private individuals) within the European Union or outside it are affected, irrespective of the sales channels used.
All stakeholders will need to adapt to these changes in the tax laws: be they online merchants, marketplaces, postal services, consumers, etc.
What are the planned changes?
🔹 The elimination of multiple thresholds concerning cross-border sales in Europe and their replacement by a single threshold.
Today, each Member State determines its own threshold (€35,000 in France; €100,000 in Germany).
On July 1, this threshold will be eliminated, and all cross-border sales irrespective of the amount will be subject to VAT based on the buyer's country of residence. (The case for both EU and non-member countries.)
The only exception will be for micro-merchants
(based in a single EU Member State) with annual sales of less than €10,000. These merchants may continue to charge VAT in the country where they are based.
🔹 Elimination of VAT exemption on packages with a value of less than €22
At present, small imported packages with a value of less than €22 are exempt from VAT and require no customs declaration.
Though this practice was not originally envisioned for commercial shipments, it is frequently used by marketplace merchants located outside the EU. This has resulted in widespread VAT fraud in Europe and a discrepancy in terms of pricing between EU and non-EU merchants.
This practice will soon be replaced by new regulations: all packages will be subject to both VAT and customs duties irrespective of their value.
With one exception:
exemption
will be possible
only
for EU-based merchants on packages with a value of
less than €150 and whose sales are declared in the OSS (
One-Stop Shop).
🔹 The introduction of three optional systems and their related electronic portals (OSS – One Stop Shop and IOSS)
As of July 1, 2021, three new systems will replace the MOSS (Mini One Stop Shop):
- The non-EU OSS system used to declare B2C services within the EU provided by companies located outside it.
- The intra-EU OSS system used to declare:
- Cross-border sales between Member States;
- Local sales concluded via marketplaces;
- B2C services within the EU provided by EU companies.
- The IOSS (Import One Stop Shop) system will enable marketplaces, EU and non-EU countries to declare the sale of goods imported from countries outside the EU with a value less than €150.
🔹 Marketplace accountability with respect to VAT
Last but not least, insofar as VAT is concerned, marketplaces themselves will be considered as having purchased and sold products via their platform.
These new regulations will be implemented to fight widespread fraud on the
part of marketplace merchants after it was discovered, on inspection, that 98% of marketplace merchants were not registered for French VAT.
To remedy this issue, it
will henceforth be the responsibility of marketplaces to collect, declare and pay VAT in lieu of the merchant.
From now on there will be two types of sales insofar as VAT is concerned:
- An exemption on sales between a merchant and the marketplace in the country in which the former is based,
- Sales between a marketplace and a private individual, subject to VAT in the product's destination country.
- In the case of European merchants: cross-border sales of goods imported from non-EU countries whose value is less than €150;
- In the case of non-European merchants: VAT is applicable to all B2C sales within the EU.
What impact will these changes have?
As the health crisis has helped e-commerce to flourish more than ever before, these changes will clearly have a significant impact on numerous stakeholders.
🔹 Marketplaces:
Marketplaces must be in a position to gather data on transactions taking place on their platforms. They will be accountable to tax authorities for transactions in which they are involved.
They have until 1 July to contact merchants and request necessary information such as: VAT number, optional registration in OSS, merchandise country of origin, type of VAT, rate of VAT on their products, etc.
These regulations will be difficult to implement insofar as they apply to each order, requiring a determination to be made for each one individually.
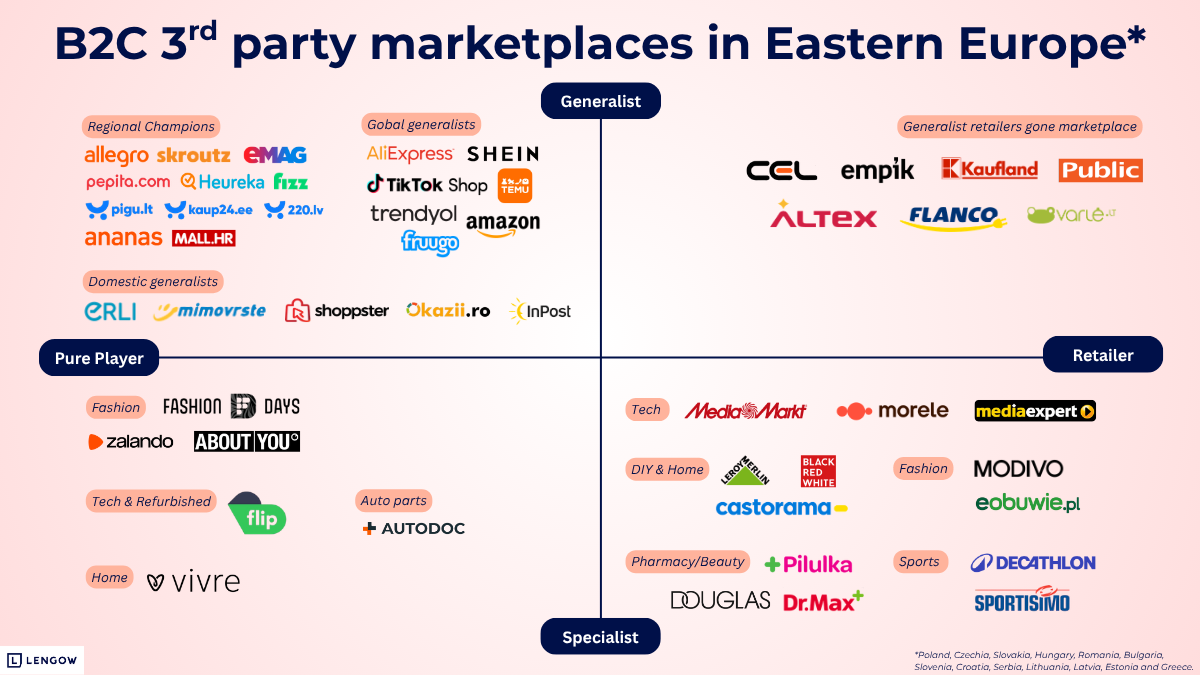
58% of Amazon's products are marketed by third-party vendors. The international marketplace maintains that it
“actively supports efforts by the French authorities to improve VAT collection"
and has "informed all partner vendors selling to customers in France of their tax obligations". (Source
JDN
)
The same holds true for Cdiscount, which has been aware of the changes for several months now.
"We support these steps to fight tax fraud and have the platforms levy VAT." This mechanism will serve to restore
competition
between the various platforms as well as competition on the same platform.
>>
However,
could there be an increase in commissions charged to merchants (who, in turn, might pass the extra fees along to consumers in the prices they ask for their products)?
🔹 Merchants:
These changes will affect all merchants operating within the EU or selling to the EU. Compliance with the guidelines of each marketplace will be required and merchant data provided in accordance with marketplace requirements.
Merchants will also need to look into registering in the IOSS/OSS and making the required tax modifications.
This represents an opportunity for EU companies to compete more fairly with merchants offering low-priced products based in China, the United Kingdom, or the United States.
For merchants based outside the EU, this will mean an increase in the total price of orders placed with them, as from now on all packages will be taxed.
🔹 Customer:
A certain number of small online orders will be more expensive when originating from a country outside the EU since packages will now be subject to VAT.
For example, as of July 1, a €10 order placed with a Chinese company will cost €12.
>> On the other hand, might prices for consumers actually decrease thanks to a decrease in EU administrative costs?
This new measure will also be accompanied by stricter customs inspections, resulting in possible delivery delays.
🔹 Lengow:
We are keeping a watchful eye on changes in every marketplace and updating our partners' flow patterns to be in a position to offer marketplaces a fully compliant solution by the July 1 deadline.
Merchants will be required to adapt product flows, incorporating data items essential to VAT collection. Such items, unnecessary in the past, will become mandatory
attributes to be input into
the API.
Example: Fnac requires that its merchants add to their product flow the field "shipping from" (= country of dispatch) when accepting an order. Lengow will ensure that this modification will be made in the flow structure associated with the distributor, Fnac, and add this field as an attribute to be filled in. This is also the case for Mirakl marketplaces.
You will find all the changes required by the marketplaces at our Help Center.
It's now up to you! If you have not yet done so, contact the marketplaces on which you sell your products right away to discover the steps you must take and implement them before 30 June 2021.
Naomi Botting
Table of content
Is your catalogue ready for AI Shopping?
Discover what AI assistants look for, how products get selected and what you can do now to stay visible in the new shopping journey.