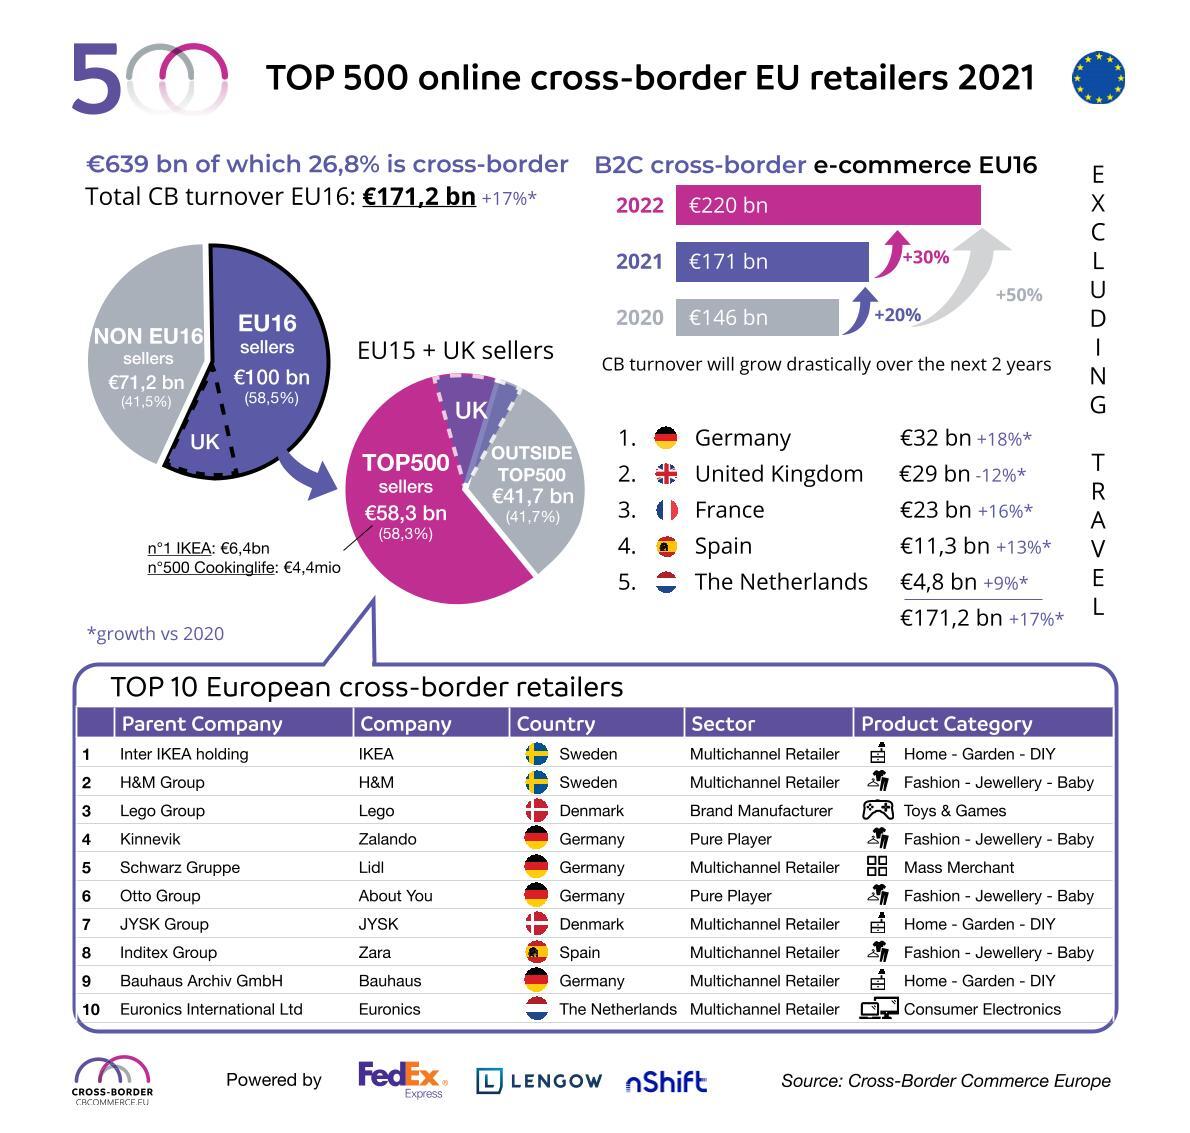
B2C online turnover from goods grew by 11.5% to €639 billion in 2021.
In 2021 cross-border e-commerce revenues (excluding travel) reached €171 billion in Europe, growing 17% year-over-year. Cross-border online sales outperformed total online sales
. A key driver is Covid-19, influencing consumers to move online for their purchases.
B2C online cross-border sales through European (incl. UK) sellers reached a record high of €100bn in 2021. This was €87.2bn in 2020, so a YTD increase of 14.6%.
An overview of the study
The study titled
TOP500 EU Retailers Cross-Border Analysis Report 2022
is a comprehensive compilation of cross-border information gathered from European retail websites. Four elements are balanced to determine the ranking:
- Cross-border online sales in Europe (15 countries within Western Europe, Scandinavia, and the United Kingdom)
- SEO performance elements that cross borders
- The cross-border score is determined by the number of active nations
- Cross-border tourists (number and proportion)
Top 10 European cross-border brands and retailers
Retailers, pure players, marketplaces and brand manufacturers make up the TOP10. IKEA, H&M, Lego, Zalando, Lidl, About You, Jysk, Zara, Bauhaus and Euronics are the 10 "best-in-class" brands and retailers for 2021.
IKEA retains its leading position in the TOP10, accounting for 20.9% of TOP500 sales, with cross-border sales of €5.5 billion, up 8% compared with 2020.
In the fourth edition of the "Top 500 Cross-Border Retail Europe", IKEA maintains its dominance. LEGO establishes a strong global strategy as a direct-to-consumer (DTC) brand.
New entrants include
Zalando
, Lidl, About You, Jysk, Zara, Bauhaus and Euronics.
Trends and analysis
Fashion and jewellery
remains the first category with a 41% share, followed by home, garden and DIY with an increase of 15% due to the pandemic. The category of personal care increased by 100%.
In the TOP500, the number of multichannel retailers has decreased, while the number of brand manufacturers intending to build their
direct-to-consumer
(DTC) channels has increased by 50%. Brand names include Lego, Nespresso, Adidas and Philips.
Luxury
brands including Richemont, LVMH, and Kering, are investing in a stronger direct-to-consumer strategy to lessen their reliance on larger markets.
Promising new challengers such as NA-KD (position 26) and Gymshark (position 105) are
digital-native vertical brands (DNVBs)
operating as
pure players
, in other words, "made on the Internet". In future editions, there are more challengers set to join the list. Looking to the United States, the market now counts over 700 DNVBs, some of which will be eager to start cross-border operations in the coming years in Europe.
Pure players, which include marketplaces, account for 47% of the TOP 500; the number of marketplaces has expanded from 28 to 42, with record sales of €20 billion (+45% YTD). The extraordinary revenue rise of European marketplaces also strengthened positions against American marketplaces.
The impact of Brexit
Cross-border sales in the UK fell by 12%, resulting in €29 billion in cross-border sales, down from €33 billion in 2020. This is due to Brexit and its impacts on VAT regulations, import duties, logistics and returns.
Consequently, Germany has surpassed the United Kingdom as the leading European cross-border country.
The presence of UK retailers in the TOP500 has dramatically decreased, 32 retailers dropping from the ranking (100 were counted in 2020, compared with 68 in 2021).
In 2022, the TOP500
counts 1.4bn monthly cross-border visitors–up from 40% year-over-year
. It’s clear that cross-border e-commerce will continue to grow quickly over the coming years. For more insights and key learnings, download the report today.